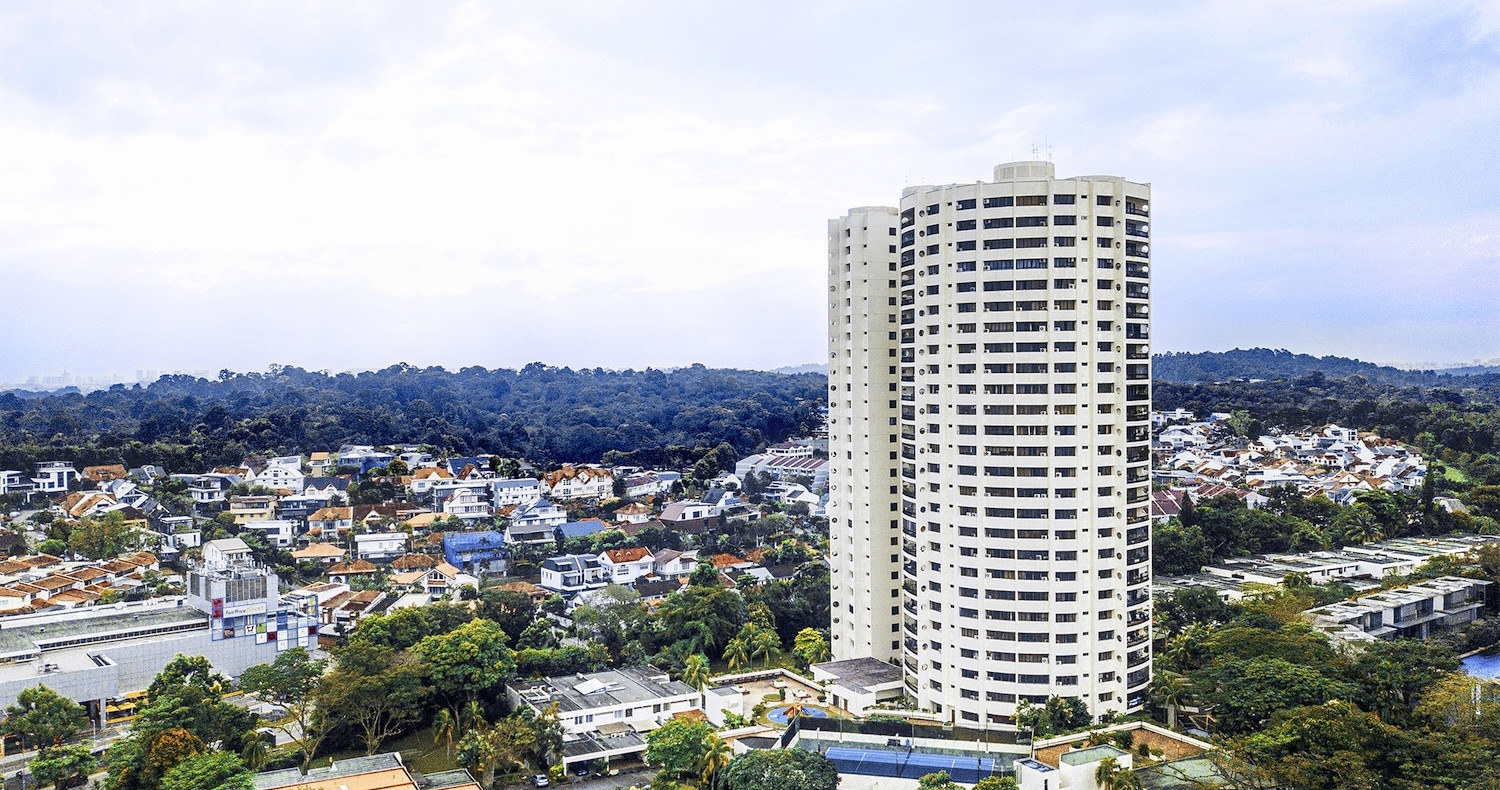
On 2 October 2025, Singapore’s en bloc market marked a significant milestone when the S$810 million collective sale of Thomson View Condominium was completed. The deal represents the largest en bloc transaction approved in Singapore since Chuan Park’s S$890 million sale in May 2023, and it showcases both the resilience of Singapore’s property market and the massive redevelopment potential of prime real estate sites.
Market Context
The redevelopment potential for older en bloc sites is strong because of Singapore’s aging housing stock: out of some 2,703 condo developments in Singapore, 836, or about 31%, are at least 30 years old. If none are sold en bloc, that number will climb to 1,160 by 2025.
Key Figures of the deal:
- Sale Price: S$810 million
- Buyers: UOL Group, Singapore Land (SingLand), and CapitaLand Development (CLD)
- Site Area: Approximately 5 hectares
- Current Units: 255 residential units
- Planned Units: Approximately 1,240 new units
- Location: District 20, Upper Thomson
- Effective Land Rate: S$1,178 per square foot ppr (developers’ total cost — see below)
Understanding the Deal Valuation
What the S$1,178 psf ppr Figure Actually Represents
The S$810 million deal, translating to S$1,178 psf ppr, includes land betterment charges and a lease upgrading premium for a fresh 99-year term. It reflects the developers’ total effective land acquisition cost, which comprises three separate outflows to two separate parties:
- Sales proceeds to former owners — the collective sale proceeds distributed among the 255 unit owners.
- Land betterment charge to the state — paid to the Singapore Land Authority for the right to intensify land use. When a site is redeveloped at higher density than before, the government levies a charge capturing part of the uplift in land value.
- Lease upgrading premium to the state — Thomson View’s remaining leasehold tenure was well short of a fresh 99 years. Developers committed to topping up the lease to a fresh 99-year period, paying a premium to the state for this right.
Add all three together, and the effective land cost works out to approximately S$1,178 psf ppr.
The 12% Price Reduction
The S$810 million sale price came in 12% below the collective sale committee’s original reserve price of S$918 million. After multiple failed tender attempts stretching back to 2013, owners were finally able to secure a committed offer from a consortium of three developers. The sale proceeded after the required 80% majority was reached. Thomson View’s case shows that en bloc attempts can stall for years before succeeding.
Owner Payouts
The S$810 million sale price was distributed among Thomson View’s 255 unit owners based on their individual unit sizes and share values:
- Largest Units: Up to S$4.9 million per unit
- Typical Units: S$2.2 million to S$4.9 million per unit
- Smallest Units: Proportionally lower, but still substantial
For most owners, these payouts represented a significant asset realisation — an opportunity to redeploy capital into other investments, upgrades, or life goals.
Why This Deal Matters
Market Signal
The completion of Thomson View’s en bloc sale sends a clear message: Singapore’s collective sale framework works, and major developers remain confident in acquisition and redevelopment opportunities. Despite the delays caused by minority objections and legal proceedings, the deal proceeded to completion — a vote of confidence in both the market and the site’s future.
Redevelopment Scale
The planned transformation is substantial. Thomson View will evolve from a 255-unit condominium to a high-density modern residential development of approximately 1,240 units — nearly a fivefold increase in housing supply. This will exemplify the evolution of Upper Thomson from a primarily low-rise residential area to a more densely developed district.
Developer Firepower
The consortium bringing together UOL, SingLand, and CapitaLand is formidable. Each brings distinct capabilities:
- UOL Group: Extensive Singapore development experience and strong brand
- SingLand: Singapore Land Group, major developer and landowner
- CapitaLand Development (CLD): The development arm of one of Asia’s largest property groups
This combination ensures the redevelopment will be executed to high standards and marketed effectively.
District 20 Transformation
Located in District 20, Thomson View occupies a strategic position near Upper Thomson MRT and close to the Orchard and Novena business districts. The redevelopment will catalyse further transformation of the broader area, influencing property values, amenities, and urban character.
Timeline to Market
- Sale Completion: October 2, 2025
- Regulatory Approvals: Pending final submissions
- Redevelopment Commencement: Expected within the next year
- New Launch Anticipated: Around 2026
Pending final regulatory clearances, construction and pre-sale marketing are expected to commence in 2026. For buyers interested in the Upper Thomson area, the upcoming Thomson Reserve launch will be a significant market entry point.
The Broader Implication
Thomson View’s en bloc sale is a reminder of Singapore’s dynamic property market. Well-located, underutilised land attracts developer interest, even when acquisition requires navigating complex legal and social processes. The completion of this deal, despite minority objections and court proceedings, demonstrates that the collective sales framework — while not without friction — delivers outcomes aligned with broader market efficiency.
For investors, residents, and industry observers, Thomson View’s transformation from a mature 255-unit condominium to a planned 1,240-unit development will embody Singapore’s continued urban evolution.
Sources: The Business Times, CapitaLand Development, Launches.sg